Executive Summary: Building an Irresistible Business Plan for Microfinance Bank Credit Assessments
Effective management of sme business plan bank loan provides commercial traders and business operators with a measurable competitive edge. Rather than navigating unpredictable informal debt cycles, adopting verified banking workflows establishes transparent cost structures and builds institutional creditworthiness.
This operational guide analyzes the underlying mechanics, regulatory standards, and practical frameworks required to maximize financial outcomes.
Key Tactical Takeaways
- Calculating net gross margins per product SKU eliminates loss-making inventory lines from store shelves.
- Shortening cash conversion cycles below 14 days multiplies annual inventory velocity by up to 3.4 times.
- Maintaining digital sales records on mobile POS terminals establishes verifiable turnover for credit underwriting.
- Building an emergency cash buffer equal to 45 days of fixed operating overhead shields retailers from supply shocks.
The Economic Imperative: Why Sme Business Plan Bank Loan Matters
For growing enterprises across key commercial hubs in Nigeria, access to structured, transparent banking infrastructure is the difference between stagnation and scalable growth. Informal credit networks and unrecorded cash transactions expose business founders to unpredictable capital drains.
Aligning operational workflows with licensed microfinance standards ensures that every naira generated actively contributes toward building creditworthiness, operational resilience, and long-term solvency.
"Digital KYC and identity harmonization are the most effective levers to eliminate transaction fraud while expanding financial access to underserved communities."
— Dr. Amina Bello, Fintech Regulation & Microcredit Policy Specialist
5-Step Roadmap to Sustainable SME Scaling
Corporate Formalization
Register business name with CAC and open a dedicated corporate bank account.
Digital Bookkeeping
Track daily revenues, expenses, and gross margins using digital accounting tools.
Cash Flow Separation
Pay founder salary instead of drawing irregular cash from business float.
Credit History Building
Access small working capital loans and repay consistently to boost credit score.
Step-by-Step Execution Blueprint for Sme Business Plan Bank Loan
To institutionalize best practices, enterprises must deploy a phased implementation sequence that minimizes operational disruption while maximizing compliance:
Phase 1: Baseline Audit
Evaluate current cash flow leakages, undocumented credit sales, and manual record inconsistencies across all daily trade channels.
Phase 2: Digital Transition
Migrate physical ledger records into verified mobile banking and POS transaction streams with full BVN/NIN validation.
Phase 3: Structured Optimization
Establish automated daily sweep accounts, negotiate reducing-balance credit terms, and conduct monthly gross margin reviews.
The 4-Stage Action Checklist for Operators
Deploy this practitioner checklist to harden operational efficiency and maximize bankability:
- Audit Cash Inflows: Map all revenue streams to identify and eliminate undocumented credit sales.
- Transition to Verified Channels: Direct all customer payments through digital bank transfers and mobile POS channels.
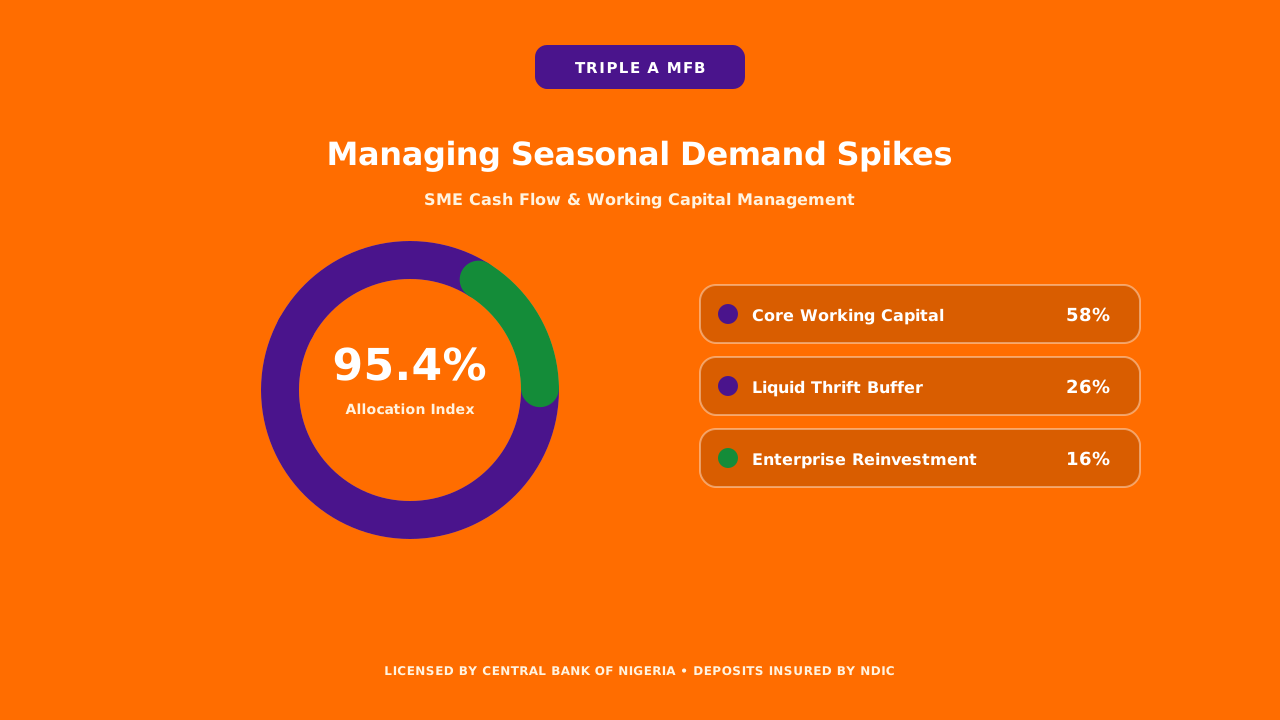
- Build an Operating Buffer: Accumulate a liquid reserve equivalent to 30 to 45 days of fixed operational overhead.
- Leverage Structured Credit: Utilize reducing-balance loans to fund bulk purchasing advantages during seasonal trade peaks.
Frequently Asked Questions on Sme Business Plan Bank Loan
Why is separating personal and business finances crucial for SME survival?
Commingling funds obscures actual profit margins and frequently leads to inadvertent spending of operating working capital, resulting in liquidity crises.
How does digital bookkeeping improve business loan eligibility?
Documented sales through digital banking apps and POS terminals provide credit officers with verifiable evidence of revenue consistency and repayment capacity.
What is the recommended size for an enterprise emergency reserve?
Retailers and commercial business owners should maintain between 30 to 60 days of fixed operating expenses in an accessible, yield-bearing savings vault.
Empower Your Business Today with Triple A MFB
Experience hassle-free banking, flexible SME loan facilities, and competitive savings yields with Triple A Microfinance Bank Limited.