Executive Summary: Transaction Monitoring and Suspicious Activity Reporting: Best Practices for Businesses
Effective management of transaction monitoring compliance provides commercial traders and business operators with a measurable competitive edge. Rather than navigating unpredictable informal debt cycles, adopting verified banking workflows establishes transparent cost structures and builds institutional creditworthiness.
This operational guide analyzes the underlying mechanics, regulatory standards, and practical frameworks required to maximize financial outcomes.
Key Tactical Takeaways
- NDIC statutory deposit insurance protects personal and business balances against unexpected institutional distress.
- Regular regulatory reporting ensures consumer protection standards are enforced across all customer touchpoints.
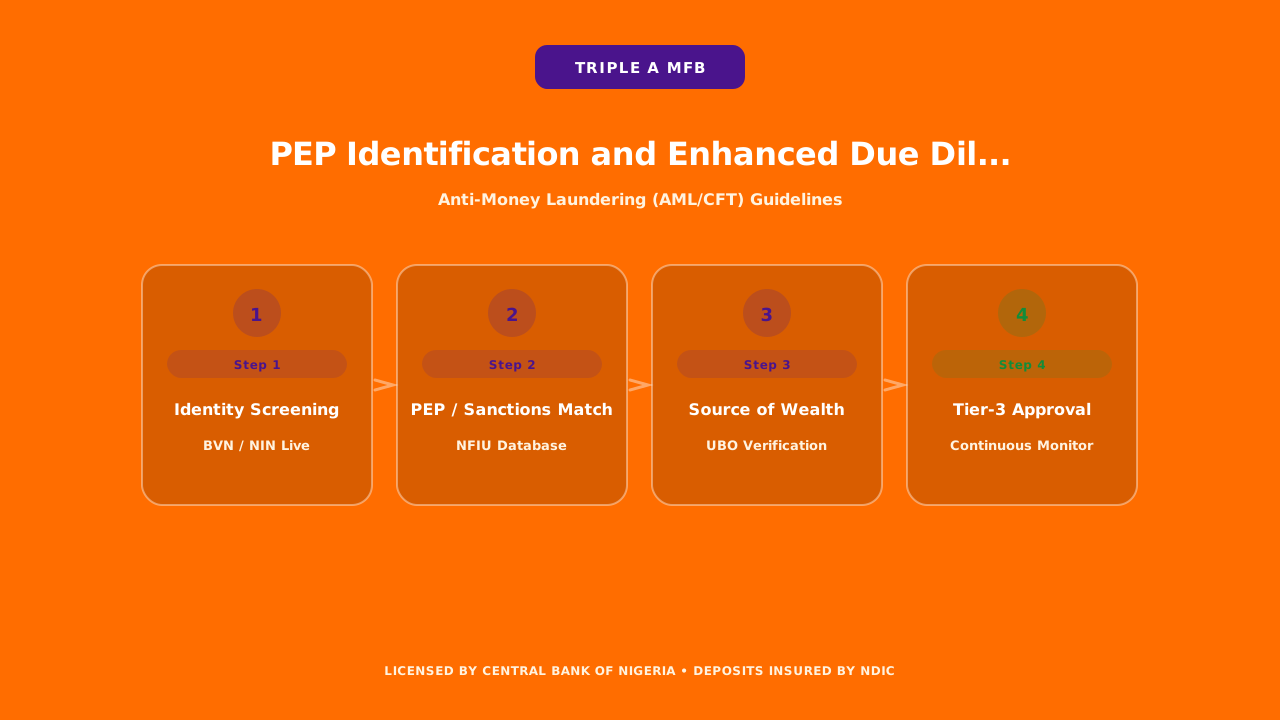
- Tier 1 to Tier 3 e-KYC compliance ensures frictionless high-volume transaction processing under CBN mandates.
- Capital adequacy ratio (CAR) monitoring by the apex bank guarantees that licensed microfinance banks maintain deep liquidity buffers.
Operational Foundations: Moving Beyond Informal Practices
Micro-enterprises frequently operate on razor-thin cash margins where a single delayed receivables batch or unexpected emergency expense can disrupt the entire supply chain. Overcoming these vulnerabilities requires establishing systematic ledger discipline and maintaining dedicated contingency reserves.
By partnering with licensed microfinance institutions, commercial operators replace volatile coping mechanisms with structured, insured, and predictable banking products designed for long-term growth.
"Microfinance is not merely about disbursing small loans; it is about building resilient financial infrastructure that protects informal traders from predatory lending cycles."
— Olayemi Cardoso, Governor, Central Bank of Nigeria (CBN)
Central Bank of Nigeria (CBN) Tiered KYC Limits
| Account Tier | Documentation Required | Daily Transaction Limit | Cumulative Balance Cap |
|---|---|---|---|
| Tier 1 (Basic) | Passport Photo, Name, Phone Number | ₦50,000 | ₦300,000 |
| Tier 2 (Standard) | Verified BVN, NIN, Basic Identity | ₦200,000 | ₦1,000,000 |
| Tier 3 (Full KYC) | BVN, NIN, Utility Bill, Valid ID | ₦5,000,000+ | Unlimited |
Comparative Analysis: Informal Methods vs. Institutional Standards
Understanding the fundamental distinction between unverified informal practices and licensed microfinance mechanisms is essential for long-term wealth preservation:
| Operational Metric | Informal / Unregulated Approach | Licensed Microfinance Standard (Triple A MFB) |
|---|---|---|
| Interest Computation | Flat rate calculations masking high effective APR | Transparent reducing-balance APR with clear amortizations |
| Depositor Protection | Zero insurance; complete capital loss risk | 100% insured by NDIC under Central Bank of Nigeria mandates |
| Credit Building | Invisible to national credit registries | Builds verified Credit Bureau (CRMS) rating for enterprise scaling |
| Transaction Security | Manual cash vulnerability & theft exposure | End-to-end encrypted digital transfers & instant settlements |
Recommended Best Practices for Sustainable Growth
Enterprise longevity requires embedding disciplined banking workflows across all daily transactions:
- Weekly Ledger Reconciliation: Cross-reference mobile app transaction histories with point-of-sale settlement summaries every weekend.
- Separation of Operating Reserves: Maintain strict partition between store inventory working capital and household living allowances.
- Fraud Prevention Hygiene: Safeguard account credentials, ensuring transaction OTPs and PINs remain strictly confidential.
- Tenor-Matched Financing: Avoid financing long-term physical equipment using high-interest ultra-short-term borrowing facilities.
Frequently Asked Questions on Transaction Monitoring Compliance
Why is biometric BVN and NIN linking mandatory for all bank accounts?
Central Bank of Nigeria mandates universal BVN/NIN harmonization to protect account holders against identity theft, eliminate ghost accounts, and enforce anti-money laundering standards.
What protections does NDIC insurance offer to depositors?
The Nigeria Deposit Insurance Corporation (NDIC) guarantees depositor funds in licensed microfinance banks, ensuring that savings remain fully insured and protected by law.
How do account tiers affect daily transfer limits?
Tier 1 accounts accommodate basic entry-level transactions, while Tier 3 accounts with full identity and address verification provide unlimited balance capacity and maximum daily transfer thresholds.
Empower Your Business Today with Triple A MFB
Experience hassle-free banking, flexible SME loan facilities, and competitive savings yields with Triple A Microfinance Bank Limited.